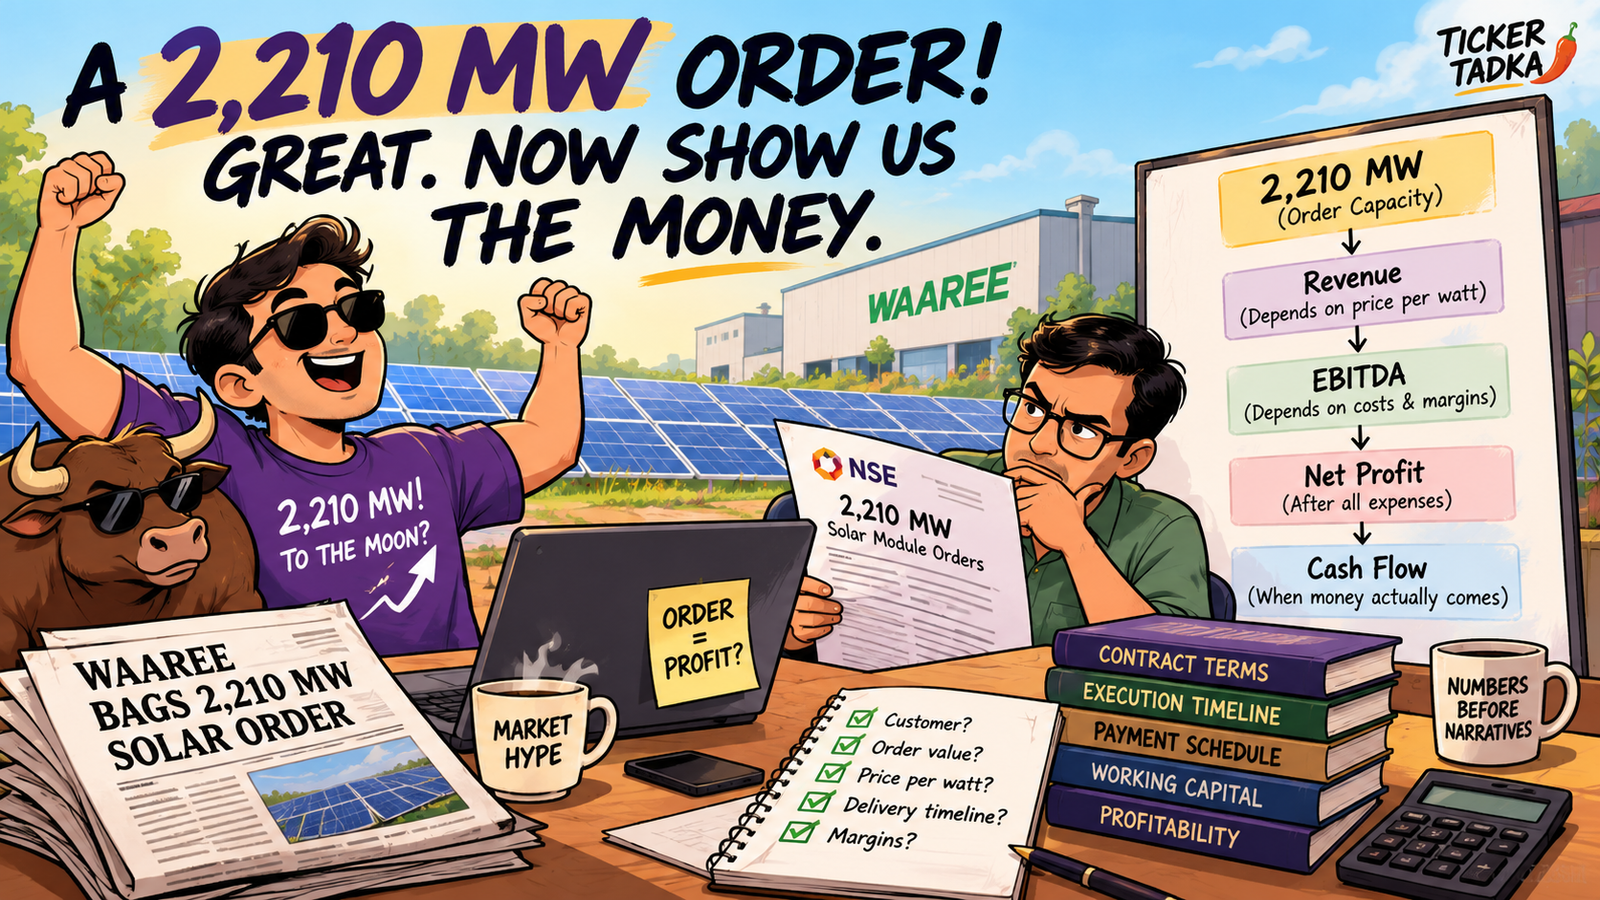
The market sees a big number. The accountant sees homework.
A company announces a massive order. The headline gets bigger, the excitement gets louder, and suddenly everyone seems to have developed a PhD in the company's future earnings.
But before we start spending profits that haven't been earned, let's ask a slightly inconvenient question:
How much money will the company actually make?
An order announcement can be excellent news. It can signal demand, strengthen a company's business pipeline and create opportunities for future growth. But an order is not the same as revenue. Revenue is not profit. And profit sitting in an accounting statement is not necessarily cash sitting in the bank.
These distinctions may not make the most exciting social-media headline. They do, however, make for better financial analysis. Let's use a real example to see why.
Exhibit A: 2,210 MW of solar modules
On 19 January 2026, Waaree Energies Limited disclosed two solar-module supply orders.
According to its original NSE filing:
- 210 MW: An order for domestic-content-requirement (DCR) solar modules from an Indian renewable-energy project developer and operator, scheduled for supply in FY2026–27.
- 2,000 MW: An order received by its wholly owned subsidiary, Waaree Solar Americas Inc., from a US utility-scale solar and energy-storage project developer and operator. Supply was scheduled from 2028 to 2030.
Add them up and we get 2,210 MW, or 2.21 GW.
That's a substantial quantity of solar-module capacity. No argument there.
But here's where we put down the celebratory chai for a moment.
The filing does not disclose the names of the customers or the monetary value of either contract. It classifies both as one-time orders and states that neither is a related-party transaction.
So we know the capacities and broad delivery schedules. We don't know the individual contract values, expected margins or profits.
The announcement has given us the headline number. The economics are still waiting backstage.
1. Megawatts are not rupees
Let's get one thing straight: megawatts measure power capacity. They do not measure the amount of money a company will earn.
A 2,000 MW order does not automatically translate into a particular rupee value. The economics depend on factors such as selling price per watt, module specifications, contractual terms and the scope of supply.
Here's the distinction investors should remember:
| Term | What it actually tells you |
|---|---|
| Order capacity | The quantity of capacity covered by the announcement. |
| Order value | The monetary value of the contract, if disclosed. |
| Revenue | Income recognised as applicable accounting requirements are met. |
| EBITDA | Operating earnings before interest, tax, depreciation and amortisation. |
| Net profit | Profit after the relevant expenses, including interest and tax. |
| Cash flow | Actual cash moving into and out of the business. |
These are connected measures, but they are not interchangeable.
Knowing the number of megawatts without knowing the selling price is a bit like knowing a restaurant served 10,000 meals but having no idea whether it charged ₹100 or ₹1,000 per plate.
Impressive footfall. Incomplete business analysis.
2. What was happening inside Waaree's financial statements?
Two days after the order announcement, on 21 January 2026, Waaree Energies released its results for the quarter ended 31 December 2025.
Its Q3 FY26 results press release reported the following consolidated figures:
| Metric | Q3 FY26 | Year-on-year change |
|---|---|---|
| Revenue from operations | ₹7,565.05 crore | +118.81% |
| EBITDA | ₹1,928.15 crore | +167.16% |
| EBITDA margin | 25.49% | 20.88% in Q3 FY25 |
| Profit after tax | ₹1,106.79 crore | +118.35% |
The company also reported an order book of approximately ₹60,000 crore in the release.
Those are useful numbers. They show that Waaree was reporting strong year-on-year growth in revenue, EBITDA and profit at the company level.
Now comes the trap.
Someone sees a reported EBITDA margin of 25.49%, looks at the new orders and decides to apply that margin to their estimated contract value. Voilà! A profit estimate appears.
The spreadsheet looks confident. The evidence does not.
We cannot use Waaree's consolidated quarterly EBITDA margin to calculate the profit on these two individual contracts.
Why? Because the margin represents the company's overall performance during a particular quarter. The new contracts have their own pricing, product specifications, costs, execution requirements and delivery schedules. Their individual economics were not disclosed.
Company-wide results give us context. They do not provide a secret window into the profitability of a particular order.
A little numerical discipline goes a long way. Occasionally, it also prevents a calculator from becoming an instrument of fiction.
3. Let's do the maths — with imaginary numbers
Suppose a manufacturer announces an order for 100 MW of solar modules.
For illustration, assume:
- Capacity: 100 MW
- Selling price: ₹20 per watt
- EBITDA margin: 10%
These are hypothetical assumptions, not Waaree's actual contract prices or margins.
Step one: Calculate illustrative revenue
One megawatt equals one million watts.
Therefore:
100 MW × 1,000,000 watts × ₹20 per watt = ₹200 crore.
For future announcements, use this formula:
Estimated revenue (₹ crore) = Capacity (MW) × Price (₹ per watt) ÷ 10
For our example:
100 × ₹20 ÷ 10 = ₹200 crore.
Step two: Estimate illustrative EBITDA
Assuming a 10% EBITDA margin:
₹200 crore × 10% = ₹20 crore EBITDA.
So our imaginary order generates ₹200 crore in estimated revenue and ₹20 crore in illustrative EBITDA.
Notice the word illustrative. We supplied the selling price and margin ourselves. Change either assumption, and the answer changes.
This is a calculation, not a revelation from the exchange filing.
For Waaree's two January orders, we don't have the disclosed contract prices or individual margins needed to perform this calculation reliably. The responsible answer is that those contract-specific figures are not disclosed in the filing.
Sometimes the most useful result from a spreadsheet is discovering which cells you cannot honestly fill in.
4. Profit is not cash. Your suppliers would like a word.
Imagine our hypothetical manufacturer delivers modules worth ₹200 crore.
Has it necessarily collected ₹200 crore in cash that day? No.
The contract may specify milestone payments, a credit period or other payment arrangements. Meanwhile, the manufacturer may already have paid for materials, labour, transport and other operating requirements.
This is where working capital enters the conversation — usually just after everyone has finished admiring the revenue number.
A company can recognise revenue and accounting profit while cash remains tied up in receivables or inventory. It may also need to pay suppliers before receiving the corresponding customer payments.
When evaluating an order, look for information about:
- Execution: When must the products or services be delivered?
- Payment terms: When is the customer expected to pay, if disclosed?
- Costs: What does fulfilling the contract require?
- Working capital: How much cash might be tied up in inventory and receivables?
- Cash generation: Is the business converting reported earnings into operating cash?
A large order can create a genuine growth opportunity while also requiring substantial execution and working-capital management.
The order announcement alone cannot tell us how smoothly that journey will go.
5. Your seven-question filing survival kit
Before treating an exchange announcement as a reason to celebrate, open the original NSE or BSE document and ask:
- Who is the customer? Is the name disclosed, or are we given only a description?
- What exactly was ordered? Identify the product or service, capacity, quantity and specifications.
- Is the monetary value disclosed? Don't confuse physical capacity with contract value.
- What is the execution schedule? An order announced today may be delivered over several years.
- What kind of contract is it? Check whether it is a one-time order or part of a recurring arrangement.
- What commercial and governance details are available? Look for disclosed terms, relevant promoter interests and related-party status.
- What remains unknown? Note missing prices, margins, payment terms and other details needed to evaluate the economics.
Apply this checklist to Waaree's 19 January filing and the picture becomes clearer. We know the two capacities, the broad customer descriptions and the supply schedules. We also know how the company classified the contracts.
We do not know the individual contract values or expected profits.
That is not a failure to analyse the announcement. It is the result of reading it properly.
The takeaway: celebrate the order, then do the homework
Waaree Energies' January 2026 announcement disclosed two solar-module orders totalling 2.21 GW of capacity. Its Q3 FY26 results, announced two days later, provided context on the company's broader financial performance.
But neither source disclosed the revenue or profit attributable to those two contracts individually.
The next time a company announces a giant order, resist the urge to turn the headline directly into an earnings forecast.
Ask what has been contracted, what the economics look like, when delivery and payment may occur, and which pieces of evidence are still missing.
An order announcement tells you that business may be coming. Good analysis asks how that business might translate into revenue, profit and cash.
And if the numbers aren't available yet? Don't manufacture them. The market already has enough imagination.
Sources
- Waaree Energies — NSE/BSE order disclosure, 19 January 2026
- Waaree Energies — Q3 FY26 results press release, 21 January 2026
Disclaimer: This article is for educational and informational purposes only. The hypothetical calculation is illustrative and does not represent the actual economics of Waaree Energies' contracts. This article is not investment advice or a recommendation to buy, sell or hold any security. Readers should consult original company disclosures and undertake their own research before making investment decisions.